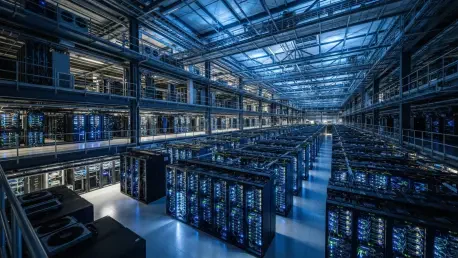
Newer neocloud providers in Singapore and Malaysia are facing intrusive physical data center inspections as part of Nvidia’s heightened vetting process. This strategic pivot by the semiconductor giant represents a fundamental shift in how silicon sovereignty is managed across global networks. By mandating that at least fifty-one percent of a provider’s GPU services must be allocated to non-Chinese entities, the company is effectively installing a demographic firewall within the digital infrastructure of Southeast Asia. This specific threshold serves as a direct response to intensifying pressure from the United States government, which has expressed growing concern over advanced hardware reaching restricted Chinese organizations through indirect internet-based channels. Instead of focusing solely on where the chips are located, the current regulatory framework now prioritizes the identity of the end user. This policy effectively closes a major loophole that allowed for the virtual export of high-performance computing power. The enforcement of these rules has fundamentally transformed the relationship between hardware manufacturers and the emerging neocloud sector.
The Mechanics of Oversight: Enforcing the Majority Rule
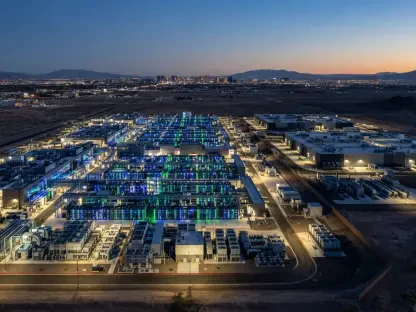
The enforcement mechanisms deployed to maintain this fifty-one percent threshold went far beyond standard corporate auditing procedures. Nvidia personnel began conducting physical site visits to data centers in Japan and Malaysia to verify the actual deployment of Blackwell-series processors and ensure they were not being redirected to unauthorized sub-leasers. These inspections included granular reviews of customer contracts and direct interviews with the technical leadership of cloud startups to confirm the legitimacy of their client portfolios. By mid-2026, the rigorous nature of these audits resulted in a substantial contraction of the approved vendor list, as many providers could not immediately demonstrate a sufficiently diverse international customer base. This hands-on approach signaled the end of an era where hardware transactions were finalized at the point of sale. Instead, the current landscape requires a continuous, verifiable chain of custody that spans the entire operational lifecycle of the silicon, forcing providers to adapt their business models.
Building on these physical safeguards, the policy also addressed the sophisticated “cat-and-mouse” maneuvers previously utilized by Chinese technology giants. Historically, firms such as Alibaba and Tencent managed to secure necessary artificial intelligence compute by leasing capacity through third-party data centers located in Australia and Japan. These legally compliant workarounds allowed them to bypass direct export bans while maintaining their development pace for large-scale language models. However, the implementation of the majority rule forced cloud operators to actively limit their exposure to these major clients to remain eligible for the latest hardware updates. By capping the percentage of revenue that could be derived from restricted regions, Nvidia effectively incentivized cloud providers to seek out Western and domestic Asian enterprise clients. This shift significantly complicated the procurement strategies for Chinese firms, who suddenly found themselves competing for a dwindling pool of legally accessible high-end compute, thereby slowing their ability to iterate on frontier AI models.
Strategic Realignments: Lessons From the Shift
The economic consequences of this regulatory tightening were felt immediately across the semiconductor supply chain and financial markets. To satisfy federal oversight requirements, Nvidia adjusted its internal financial reporting structures to meticulously track the geographical and national origin of every dollar generated through its data center division. This granular data allowed the company to demonstrate compliance to the Department of Commerce, even if it meant sacrificing short-term revenue from formerly lucrative contracts in the Asia-Pacific region. In fact, by the second quarter of 2026, the company successfully reduced its approved Asian customer list by over fifty percent, prioritizing long-term market access over immediate sales volume. For investors, these developments introduced a new layer of volatility as they weighed the risks of restricted market access against the stability of maintaining a dominant position in the Western-aligned tech ecosystem. The strategic sacrifice of certain market segments became a necessary trade-off to protect the integrity of the broader technological infrastructure and ensure the security of critical AI tools.
The resolution of these tensions established a new blueprint for the global technology trade that prioritized national security over unhindered commercial expansion. Stakeholders who thrived in this environment recognized the necessity of building transparent, sovereign supply chains that anticipated regulatory shifts rather than merely reacting to them. Strategic roadmaps for 2026 and beyond incorporated rigorous compliance benchmarks that integrated legal vetting directly into the hardware procurement process. Industry leaders realized that the separation of compute power was not just a technical challenge but a geopolitical imperative that required proactive engagement with government standards. These firms invested heavily in auditing technologies that provided real-time visibility into GPU utilization and end-user demographics, ensuring they remained on the right side of the majority rule. Consequently, the industry moved toward a more fragmented but controlled ecosystem where the flow of innovation was moderated by strategic alignment. This period of transition ultimately taught organizations that the most valuable asset in the modern tech landscape was not just the hardware itself, but the verified trust associated with its usage.