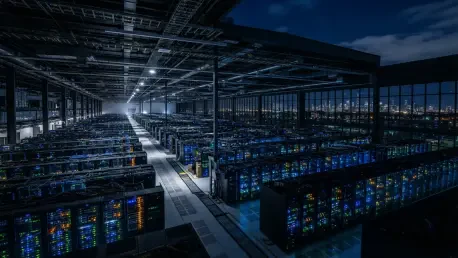
The scarcity of shovel-ready sites with secured power permits has created a significant competitive advantage for established market incumbents. As global digitization accelerates, the role of the data center has shifted from a peripheral real estate sub-sector into the fundamental backbone of the modern economy. This transformation reflects a deeper realization among institutional investors that these facilities are more akin to vital utilities than traditional commercial properties. The current landscape is defined by an insatiable appetite for compute capacity, yet the physical reality of building such infrastructure faces unprecedented hurdles. From power grid limitations to stringent local regulations, the barriers to entry have never been higher. Consequently, the industry is seeing a consolidation of power among those who can navigate the complex intersection of electrical engineering, government relations, and massive capital deployment. This shift toward an infrastructure-driven model represents a maturity in the asset class that demands a more sophisticated approach to investment.
Analyzing the Evolving Data Center Investment Landscape
Multi-Dimensional Growth: Driving Digital Consumption
The explosion of digital data creation has fundamentally altered the trajectory of the infrastructure market, with volumes increasing by nearly 20,000 percent since 2010. This surge is not a temporary phenomenon but a structural shift in how society and businesses function, leading to a projected annual growth rate of 14 percent through 2030. By that time, global capacity is expected to approach 200GW, a scale that was almost unimaginable just a decade ago. While various factors contribute to this expansion, the underlying constant is the transition of essential services to the cloud. From financial transactions to healthcare records, the reliability of data centers has become a non-negotiable requirement for modern life. Investors now view these assets as critical conduits for economic activity, providing a level of stability and growth potential that distinguishes them from more volatile sectors. This multi-dimensional demand profile ensures that the industry remains insulated from minor economic fluctuations, as the need for data processing power continues to grow regardless of broader market cycles.
The Synergy: Cloud Foundations and AI Innovation
While cloud computing remains the foundational engine of the industry, the rise of Artificial Intelligence has introduced a sophisticated new layer of demand. It is essential to distinguish between the two primary phases of AI development: model training and live inference. Currently, the market is heavily skewed toward massive training environments, which require high-density campuses often located in regions where land and power are more readily available. These facilities are designed to handle immense workloads over long periods, making them the primary focus for hyperscale developers. However, as AI models become more integrated into daily applications, the focus is beginning to shift toward inference. This phase requires low latency and proximity to end-users, which will eventually pull demand back toward major metropolitan hubs. This dual-layered demand ensures a diverse and resilient market, as providers must balance the needs of traditional cloud services with the intense, evolving requirements of the AI ecosystem. The ability to cater to both creates a robust long-term outlook for existing facilities and new developments alike.
Navigating the Dynamics of Scarcity and Power
Infrastructure Constraints: The Energy Bottleneck
The industry is currently grappling with a severe supply crunch that has driven vacancy rates to historic lows across major global markets, including both the United States and Europe. This shortage is no longer a matter of construction speed but is primarily a consequence of bottlenecks in the energy grid and the regulatory environment. Utility interconnection timelines, which represent the time needed to hook a facility to the power grid, now frequently stretch between 24 and 48 months. This delay is exacerbated by a broader surge in electrical demand from the manufacturing sector and the general electrification of the economy. For context, utility load growth is projected to jump to 15.8 percent over the next five years, following decades of near-stagnant demand. Power availability has essentially become a “license to operate,” and by 2027, an estimated 40 percent of existing AI-capable data centers will be constrained by energy limitations. This environment turns power into the ultimate commodity, where the possession of a secured energy allocation is more valuable than the physical building itself.
Regulatory Frameworks: Overcoming Social Hurdles
Beyond the technical challenges of energy procurement, social and political hurdles are increasingly stalling development projects worldwide. Public sentiment and “not-in-my-backyard” opposition have led to billions of dollars in delayed or blocked projects across various jurisdictions. Local governments are becoming significantly more selective about permitting, focusing intensely on the environmental impact, water usage, and community benefits of these massive facilities. Between 2024 and 2025, approximately $64 billion worth of U.S. data center projects faced significant delays or outright cancellations due to community opposition. These barriers to entry create a massive advantage for incumbent players and investors who already possess the necessary infrastructure and approvals. Navigating these complexities requires a deep understanding of local politics and a commitment to sustainable development practices. As the regulatory landscape becomes more crowded, the ability to maintain strong relationships with municipalities and utility providers has become a critical differentiator for successful long-term investment strategies.
Financial Evolution and Institutional Strategy
Cash Flow Stability: The Infrastructure Model
One of the most compelling reasons for the sector’s reclassification is the changing nature of its cash flows and risk profile. Historically, data centers were often built on a speculative basis, but the modern hyperscale model is defined by aggressive pre-leasing to high-credit technology giants. New capacity is typically 70 to 90 percent pre-leased before construction is even finished, often to “blue-chip” tenants with exceptionally high credit ratings. Lease terms have also elongated significantly, with 10 to 15-year commitments becoming the standard for major installations. These long-duration contracts, combined with high tenant retention rates, give data centers a financial profile that more closely resembles contracted infrastructure—like pipelines or power plants—than traditional office or retail space. For institutional investors, this translates into high income visibility and reduced leasing risk. This stability is particularly attractive in a volatile economic climate, as the revenue streams are backed by the world’s most well-capitalized corporations. This evolution has successfully bridged the gap between real estate and essential utilities.
Upstream Migration: Strategic Development Cycles
As stabilized, ready-to-use data center assets become increasingly rare and expensive, institutional capital is moving “upstream” into the earlier stages of the asset lifecycle. Rather than waiting to purchase completed buildings, investors are now allocating capital at the conception, design, and initial development phases. This shift is driven by necessity but offers the potential for higher returns as the “development spread” becomes more pronounced. However, entering at this stage requires a much higher degree of technical expertise and a significantly larger capital commitment than in previous market cycles. Modern projects are far more capital-intensive, with power infrastructure alone accounting for up to 50 percent of total costs. Furthermore, the financial stakes of simply entering the queue for power are rising; utility deposits of $25 million to $75 million are now common requirements just to secure future energy allocations. This high-cost environment favors large-scale institutional players who can stomach high upfront expenditures and manage the technical complexities inherent in large-scale industrial-scale developments.
Operational Excellence and Market Outlook
Execution Strategy: Delivering in a High-Stakes Market
In an era where demand is virtually guaranteed but supply is restricted, the ability to deliver a finished project from start to finish has become the ultimate differentiator. Success in the current environment no longer belongs simply to those with the most capital, but to those who can successfully navigate the physical bottlenecks of power procurement and community relations. Strategic partnerships with experienced developers have become essential, particularly as facilities must now accommodate the complex high-density cooling requirements of modern AI hardware. Shovel-ready sites and existing shells with secured power are now the most valuable commodities in the digital economy. The industry has reached a point where operational expertise is the primary driver of value creation. Those who mastered the intricacies of utility negotiation and high-density design were able to capture significant market share while others remained stalled in the permitting phase. This focus on execution ensures that the most capable operators are the ones who define the future of the digital landscape, turning technical challenges into sustainable competitive advantages.
Long-Term Vision: Preparing for the Utility Era
The transition of the data center market into a vital infrastructure sector was effectively completed through a series of strategic shifts in capital allocation and operational focus. Forward-thinking investors recognized that the traditional real estate model was insufficient to meet the demands of a world powered by artificial intelligence and ubiquitous cloud services. They shifted their focus toward securing power pathways and fostering transparent community partnerships well in advance of construction. This proactive approach allowed them to bypass the grid congestion that hampered smaller, less prepared competitors. Moving forward, the most successful entities focused on the integration of sustainable energy solutions and advanced cooling technologies to ensure long-term viability. They also prioritized the development of secondary markets where power was more abundant, effectively creating new hubs of digital activity. By treating these facilities as essential utilities, the industry aligned itself with the long-term trajectory of global digital transformation. This strategic realignment provided the foundation for a more resilient and predictable investment environment that favored technical depth and operational foresight.